Investment properties · Enough by Design
Income property that pays you to hold it
Cash-flow-positive small multi-family in Northern BC's energy towns. I own here myself, and I buy for clients the way I buy for me: cash flow first, conservative leverage, durable operations.
~7%Cap rates on well-bought Fort St. John duplexes, vs. about 4% in Vancouver
1.25×Minimum debt coverage I'll buy at
80%Maximum leverage on a purchase, and only when the deal clears 1.25×
How it works
A little of your capital, a lot of building, and a business inside it
You use some of your own capital plus a mortgage to buy a large, likely appreciating asset that contains a working rental business. The rent covers the expenses and the mortgage, and leaves cash in your pocket. Your investment isn't the purchase price: it's the cash up front, and that's the number whose performance we measure.
01
Cash flow
Rent left over after every expense and the full mortgage payment. It's what lets you hold through a soft market without feeding the property.
02
Principal paydown
Every mortgage payment includes principal, paid by your tenants' rent. Your equity grows each month whether the market moves or not.
03
Appreciation
Real over the long run, but the least reliable of the three. I treat it as a bonus, never as the reason to buy.
I've never believed in advising clients on something I haven't done myself. My wife and I own and manage our own cash-flowing properties in Northern BC, and I read the same statements my clients do.
How I buy
The rules that keep leverage safe
Leverage magnifies gains and losses. These are the tests a property has to pass before I'll recommend it to a client, or buy it myself.
- Cash flow firstPositive at today's rates, after a real vacancy allowance, management and a capital reserve. No property that needs appreciation to work.
- Debt coverage1.25× or better on forward income at the contract rate. If a deal can't reach that, add equity or pass.
- Conservative leverageUp to 80% loan-to-value on purchases, only when the deal clears the coverage test. Refinances to 75–80% under the same discipline, and a cash reserve that's never funded from refinance proceeds.
- Newer buildingsI prefer newer, more appealing properties that stay tenanted even in weaker markets, with fewer capital surprises.
- Real catalystsTowns with large, funded projects and jobs behind them, not just a cheap price.
- Local managementProfessional property management in place from day one, with monthly statements you can check against the plan.
Where I invest
Northern BC, where the rent pays the mortgage
I focus on a small number of towns where I know the buildings, the managers and the economics first-hand.
Fort St. John · my main market
Get paid to hold
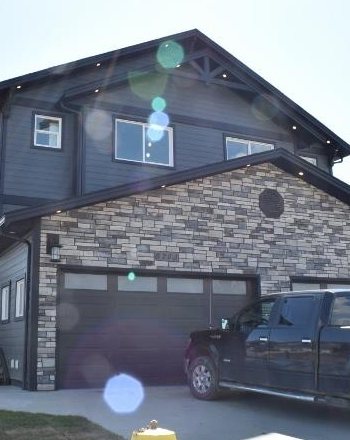
At the source of Canada's LNG build-out, a decade behind its northern peers on price, and now turning. Eight of my own doors are here, with the same local manager my clients use.
Read the investor brief →Kitimat and the north coast
The other end of the pipeline
LNG Canada's export terminal town. I own here too, and bring clients opportunities when the numbers and management are right.
See current opportunities →Working together
From first call to keys, and after
- 01Strategy callYour capital, timeline, return targets and ownership structure.
- 02Capital planBuy box, sequencing and a financing path that scales past residential lending limits.
- 03SourcingOn- and off-market properties, each run through my acquisition gate before you see it.
- 04OnboardingInspection, local management, tenant placement and reporting set up from day one.
- 05OversightStatements checked against the plan. Equity recycled only at renewals, and only through the gates.
Research
Read before you call
- Investor briefFort St. John: get paid to holdThe case, the catalysts, my own properties' numbers, and the risks stated plainly.Read →
- StrategyThe real estate flywheelWhen recycling equity beats buy-and-hold over 10 years, and the rules that keep it safe.Read →
- StrategyIncome now, or a bigger engine laterWhat C$600,000 does over 20 years, and what changes if you live on the cash flow instead of reinvesting it.Read →
- The basicsLeverage, cap rates and cash-on-cash, explainedMy plain-language primer on how leveraged property investing works and how to measure it.Read →
- Market insightVancouver, read clearlyFor investors deciding what to do with Vancouver equity: the monthly update and quarterly report.Read →
Is it for you?
Who this suits, and who it doesn't
Usually a good fit
- You've built equity in Vancouver and want it working harder, with income
- A 10-year-plus horizon, steady income and room for a cash reserve
- You want a hands-off owner experience with professional management
- You'd rather own real buildings than another fund
Probably not, or not yet
- You need the money back within a few years
- Every dollar is committed, with nothing left for a reserve
- You're looking for a quick flip or appreciation alone
- One regional economy feels like too much concentration for you
Next step
Let's see what your equity could do
A 30-minute call, Zoom or meeting: your capital, your timeline and your targets, and an honest read on whether this fits. If it doesn't, I'll tell you.
Cap rates and operating rules are from my Fort St. John investor brief and flywheel analysis (October 2026). For education and discussion only; not individualized financial, legal or tax advice. This describes direct property ownership, not a pooled investment or securities offering. Leverage magnifies losses as well as gains; cash flow can be negative and capital can be lost. Obtain independent advice.
 The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.